Consultation
Indication/history
Why the appointment occurred
Provision to examine
Exam-fee benefit and exclusions
Bounded evidence
Selected fee benefits can matter
Question left
Was the relevant option selected?

Follow a weight-management visit from diagnosis to its separate invoice lines.
Use these checkpoints to frame the literal question before reading the full guide.
Pet insurance coverage for obesity treatments cannot be answered by calling the whole visit “medical.” A consultation, diagnostic work, prescribed food and follow-up monitoring may receive different treatment under the contract. A documented diagnosis can explain the reason for care, but it does not cancel a food exclusion or a prior-condition restriction.
The sections below show how to verify the answer and what can change it.
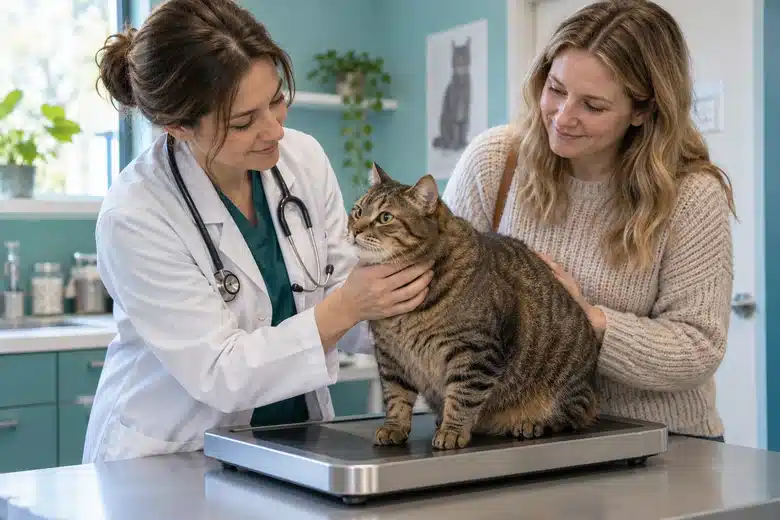
Imagine an owner brings a cat for a weight-management consultation. The veterinarian assesses its condition, considers whether diagnostic testing is appropriate and recommends a monitored feeding plan. This scenario does not diagnose a real pet or prescribe a diet.
AAHA’s 2021 guidelines recommend individualized nutritional assessment, including body and muscle condition. That supports treating weight care as a clinical process rather than judging a pet by appearance alone. It does not tell an insurer which expenses to reimburse.
| Invoice item | Indication/history | Provision to examine | Bounded evidence | Question left |
|---|---|---|---|---|
| Consultation | Why the appointment occurred | Exam-fee benefit and exclusions | Selected fee benefits can matter | Was the relevant option selected? |
| Diagnostics | Reason recorded by veterinarian | Eligible testing and condition definition | No obesity-specific approval established | Does this investigation meet the clause? |
| Prescription diet | Exact product and purpose | Food exclusion | Specimen 5.A.6.o excludes prescription foods | Does another applicable form differ? |
| Monitoring | What each return visit provides | Consultation/benefit limits | Not automatically one covered package | How is each charge categorized? |
The Pets Best Alabama-labeled public specimen excludes prescription pet food in section 5.A.6.o. This demonstrates why a prescribed product need not be insured; it is not a universal rule for every insurer or state.
Keep policy terms, deductible, reimbursement and limits beside the quote so the comparison stays consistent.
Keep the first recorded weight concern, earlier advice, symptoms, testing, enrollment effective date and treatment dates distinct. If the recent diagnosis follows earlier related signs, the timing question is not solved by the date printed on the newest invoice. A factual timeline lets the insurer identify the provision it is applying without asking the owner to make a medical causation judgment.
Assume an invented visit costs $240: $80 for consultation, $100 for tests and $60 for food. Suppose this fictional contract accepts the first two lines, excludes the food, has $100 deductible remaining and reimburses 80% after it. With sufficient limit, payment is ($180 − $100) × 80% = $64. The owner retains $176, plus premiums. If the exam fee were also excluded, the eligible amount would be $100 and this assumed formula would pay nothing.
Those numbers are not clinic prices, a named insurer’s terms or an expectation of approval. They show why retaining an itemized estimate matters. The same veterinary plan can have different insurance arithmetic when its expense classifications change.
Continue medical decisions with the veterinarian rather than reshaping a care plan around an assumed claim. For insurance review, keep the original medical description and invoice accurate. A wellness allowance, if present, also needs its own named benefit; it should not be treated as a general weight-loss fund.
No automatic conclusion follows. The public specimen examined here excludes prescription food; other applicable wording must be read on its own.
It explains a bounded public-policy example and an invented calculation, not an individual claim outcome.
Keep the policy terms beside the price, then continue to rates when the comparison is clear.